Blog//Silver Tsunami: Essential Strategies

Share
Navigating Cognitive Decline and the Silver Tsunami: Essential Strategies for Financial Advisors
As a financial advisor, I’ve noticed a shift in the landscape that demands our attention and proactive engagement. With life expectancy on the rise, we are seeing a larger elderly population, which brings about a new set of challenges and opportunities. Cognitive decline, including conditions such as dementia, is becoming more prevalent, and addressing these issues is crucial not only for the well-being of our clients but also for the sustainability of our practices. Here’s how we can navigate these changes effectively.Recognizing the Challenge
- Aging Population and Cognitive Decline:
- Our clients are living longer than ever before, resulting in a larger elderly population.
- With aging comes an increased likelihood of cognitive decline. By age 85, over half of the population may have some form of dementia, with the risk doubling every five years after age 60.
- Interestingly, women are statistically more susceptible to dementia than men.
- Client Scenarios:
- We might notice elderly clients exhibiting unusual behaviour that’s out of character.
- Preparing generally healthy clients aged 70 and above for potential incapacity is essential.
- Providing support for clients who are caregivers for parents with dementia is becoming increasingly important.
The Silver Lining: Opportunities for Advisors
- Canada’s Silver Tsunami:
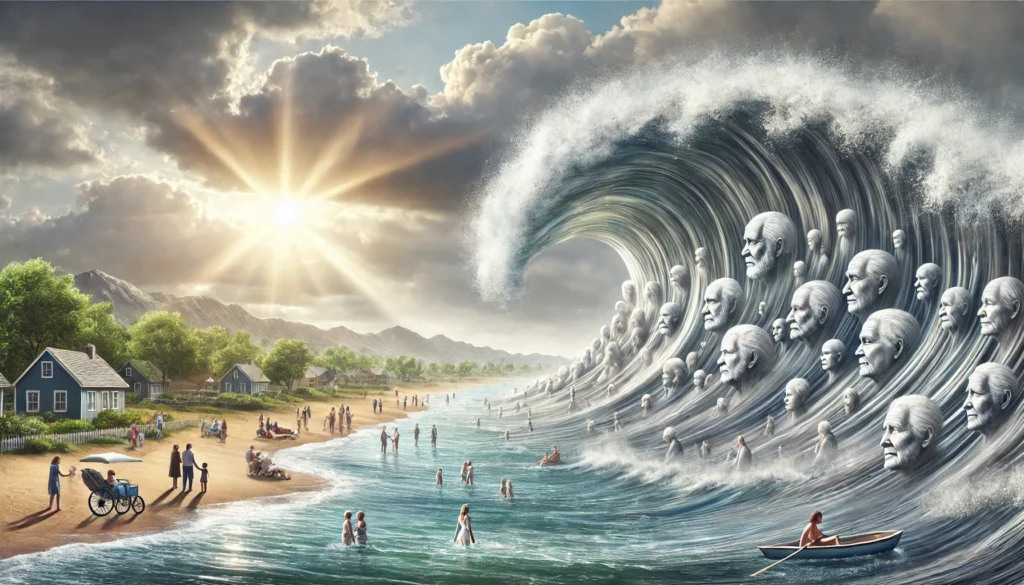
- Demographic trends indicate a significant aging population, often referred to as the “silver tsunami.”
- This presents a market opportunity for us to cater to the unique needs of older adults.
- Emerging Market Opportunities:
- Wealth is disproportionately held by older adults, making them key clients for us.
- By supporting our clients in preparing for cognitive decline and protecting their assets, we can enhance client relationships and retention.
- The Great Wealth Transfer:
- A significant amount of wealth, estimated at $750 billion, is expected to be transferred to Canadian baby boomers by 2026.
- Engaging with the heirs of senior clients and addressing cognitive issues proactively can help us retain these assets through intergenerational wealth transfer.
Establishing the Gold Standard: Best Practices
- Recognition:
- Identifying the red flags of cognitive decline and financial exploitation is crucial.
- Getting to know our clients deeply is essential. We should understand their behavior, intentions regarding gifting, and future financial support plans.
- Preparation:
- It’s essential to document and prepare clients and businesses for potential incapacity while clients are still capable.
- Early documentation and conversations about mental capacity deterioration are vital.
- Protection:
- We must protect our clients, ourselves, and our businesses by recognizing signs of cognitive decline and exploitation.
- Providing support to clients’ families and guiding them toward appropriate resources can enhance our value.
Key Takeaways for Advisors
- Understand Client Behavior:
- Regularly interact with clients to recognize any changes in behavior, mood, or investment practices.
- Pay attention to signs such as confusion, mood swings, or changes in financial decisions.
- Be Prepared for Financial Exploitation:
- Watch for red flags such as reluctance to discuss finances, sudden involvement of previously uninvolved relatives, or unexplained changes in financial documents.
- Build Deep Relationships:
- Developing strong relationships with clients and their families can help us navigate challenging conversations about cognitive decline and incapacity.
- Position ourselves as trusted partners who can provide comprehensive support beyond financial management.
You May Also Like
Federal Budget 2025: What It Means for High-Net-Worth Canadians, Business Owners & Investors
For business owners, incorporated professionals, and high-income families, this year’s budget doesn’t deliver sweeping tax rate changes, but it does…
Read more
Understanding the Impact of Trudeau’s Resignation on Capital Gains Tax
Capital Gains Inclusion Rate (CGIR): What’s Changed? In the 2024-2025 federal budget, a proposed increase in the Capital Gains Inclusion Rate to 66…
Read more
Using Life Insurance as a Charitable Giving Tool
Another method involves donating an existing policy to a charity during the donor’s lifetime. While more complex from a tax perspective, this…
Read more
Minimizing Tax Burdens and Maximizing Liquidity
The Role of Life Insurance in Estate Planning: Minimizing Tax Burdens and Maximizing Liquidity Estate planning is an intricate process involving two…
Read more